“Do I need to mention that old surgery again? And does a complaint without an official diagnosis count?”
At existing conditions under a health insurance in Spain Complete and honest answers are essential. The medical questionnaire does not only cover serious diagnoses. Past complaints, examinations, medication and treatments can also be relevant when the insurer asks about them.
Having an illness does not automatically mean that your application will be rejected. The insurer assesses each application individually.
Short answer: answer exactly what is asked on the medical questionnaire and, in case of doubt, clarify in writing what you need to report. The possible outcome is full acceptance, additional questions, adapted terms and conditions, exclusion or rejection. Only the insurer can decide that.
In this article
What is an existing condition?
By pre-existing condition, an insurer usually means a health condition that existed before the policy was concluded or entered into. Whether existing conditions count depends on the questions the insurer asks and your personal situation.
At existing conditions under a health insurance in Spain can count for more than a formally established disease. Depending on the question asked, the following may also be relevant:
- complaints for which you visited a doctor;
- medication that you are using or have used;
- Previous surgeries or hospital admissions;
- ongoing investigations;
- recommended or planned treatments;
- chronic or recurrent symptoms.
Why are you being given a medical questionnaire?
A private health insurer assesses the risk at the time of the application. To do so, it uses a declaración de salud or medical questionnaire.
The assessment of existing conditions under a health insurance in Spain can lead to:
- acceptance according to the standard conditions;
- a request for medical reports or additional explanations;
- acceptance with a specific exclusion;
- acceptance under modified conditions;
- deferment or rejection of the application.
None of these outcomes automatically follows from a single diagnosis. The nature of the condition, current treatment, stability, the product requested, and the acceptance rules all play a role.
What exactly do you need to report?
According to the Spanish law on the insurance contract The applicant must correctly answer the insurer's questions about the risk being assessed. Where possible, provide clear data, diagnoses, medication, and the current situation. If you are unsure of an answer, note it and ask how to complete it correctly.
For existing conditions under a health insurance in Spain It helps to collect your medical information in a clear overview in advance.
Prepare your medical information
| Subject | What are you noting? | What could be useful? |
|---|---|---|
| Diagnosis or complaint | What happened, when it started and your current situation | A recent medical report, if you have it |
| Medication | Name, dosage and how often you use it | An up-to-date overview of medications |
| Surgery or hospitalization | Reason, date and recovery | The discharge or operation report |
| Research | Completed, ongoing or planned and the current status | The result or appointment confirmation |
| Treatment or control | Completed, underway or still planned | A recent report from the doctor or specialist |
| Completed questionnaire | Check that all answers are complete and correct | Keep a copy of the final version yourself |
Do not answer more broadly than asked for, but also do not deliberately leave anything out. An incomplete answer could cause discussion later when care is requested.
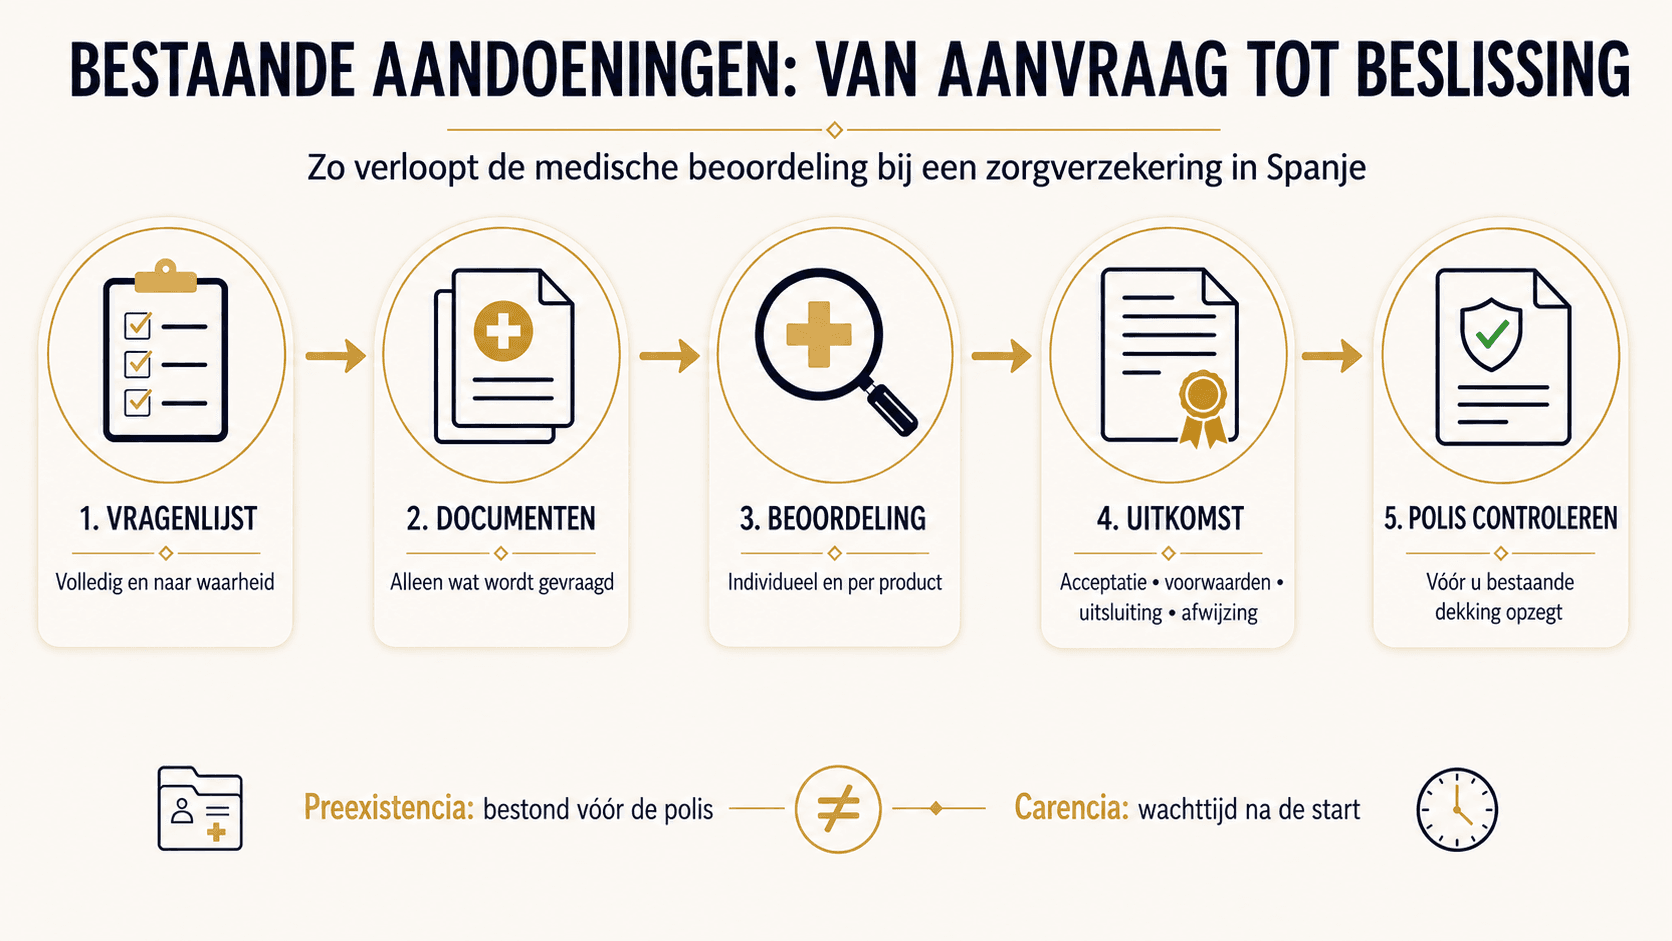
Is an existing condition the same as a waiting period?
No. These are two different concepts.
- Preexistence: a condition or health situation that existed before the insurance and can affect acceptance or coverage.
- Shortage: a contractual period after the entry date in which a certain covered benefit cannot yet be used.
At existing conditions under a health insurance in Spain An exclusion can remain in effect as long as the policy specifies. A waiting period generally ends after the period specified in the policy. Read our article about Terminating your health insurance in Spain on time for more explanation about this difference.
Why verbal reassurance is not enough
An intermediary can help you understand the procedure, but the medical acceptance lies with the insurer. Therefore, ask for the final decision and any exclusions in writing.
Check before signing:
- which specific condition is excluded;
- either the condition itself or also its consequences are excluded;
- which carencias apply;
- or whether additional information is still being assessed;
- from which date the policy takes effect;
- which personal conditions are included in the policy.
At existing conditions under a health insurance in Spain Is the text on the policy more important than a general product description?.
Why applying in time can be wise
A private health insurance is intended for future risks. Those who wait until an examination, diagnosis, or treatment is already underway may have fewer options.
Applying in a timely manner does not guarantee acceptance. It does give you time to gather information, ask questions, and understand the outcome before you terminate your existing coverage. Never cancel an existing insurance policy before the new application has been accepted in writing and the effective date is determined.
More information about the base can be found on our page about the health insurance in Spain.
Summary
At existing conditions under a health insurance in Spain It’s not about gambling what the insurer considers important. You answer the questions carefully, provide the requested documents, and wait for the written medical assessment.
An earlier claim does not automatically mean rejection. However, a new policy also does not automatically cover all care that was necessary or foreseeable before the policy's effective date. Therefore, always check in writing before the effective date which conditions and treatments are and are not covered.
Frequently Asked Questions
Do I have to report an old condition if I no longer have any complaints?
If the medical questionnaire asks for it, yes. Mention that the treatment has been completed and since when you have been symptom-free. The insurer will assess the information.
Does a complaint without a diagnosis count as an existing condition?
That is possible. Symptoms, ongoing investigations, or medication may be relevant, even without a definitive diagnosis. Follow the exact question and ask for clarification if in doubt.
Are existing conditions always excluded?
No. The outcome varies per application, condition, product, and insurer. There may be full acceptance, exclusion, additional assessment, or rejection.
Can an intermediary guarantee my medical acceptance?
No. Only the insurer makes the medical acceptance decision. An intermediary can explain the process and help check that the documentation is complete.
What happens if I forget information?
Report a mistake or omission as soon as possible and in writing. Do not wait until you need treatment. The insurer determines what consequences the supplement will have.
Can I start using healthcare services while the application is being reviewed?
Not based on a policy that has not yet been definitively accepted and entered into. Maintain your existing coverage until the new situation is clear.
Do you want to prepare an application carefully?
If you don't have a policy yet and have questions about existing conditions under a health insurance in SpainGrupoXandra helps Belgians and Dutch people better understand the medical questionnaire, possible outcomes, and policy conditions. The medical decision always remains with the insurer.
Check our Health insurance in Spain.
or send an email to [email protected] for personal advice and more information.